

Chinese Yuan Outlook: Inflation and Trade Test the Case for Further Gains
China’s inflation and trade releases will test the Yuan’s resilience as Beijing tolerates appreciation despite a firmer Dollar and renewed trade pressure.
China’s inflation and trade figures on Wednesday will test whether the Yuan’s strength is supported by a broader improvement at home, or remains chiefly a product of export earnings and Beijing’s tolerance for appreciation.
China’s official release calendar confirms September consumer and producer prices are due on 14 October.
Crédit Agricole’s 9 October calendar records consensus expectations for CPI inflation to rise to 1.1% from 0.8%, and producer-price inflation to 4.4% from 3.8%.
Faster factory-price inflation would not by itself demonstrate a recovery in domestic demand.
The Yuan is resisting broader Dollar strength
The Yuan’s gains also carry political significance as European officials challenge the scale of China’s trade surplus.
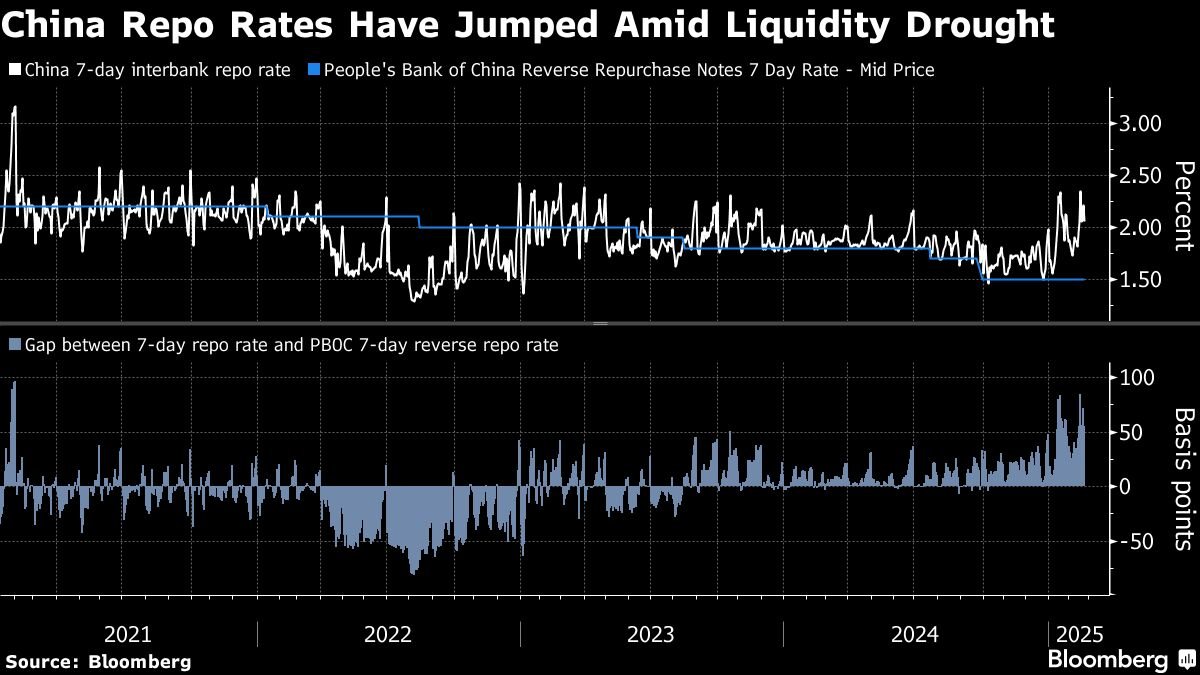
MUFG’s Derek Halpenny writes: “This mounting pressure looks to be encouraging China too allow renewed gains. Recent PBoC fixing in USD/CNY indicate a desire to keep CNY on a strengthening path despite the broader gains for the dollar. EUR/CNY is 10% lower from the January high and we see near-term scope for further declines.”
Nomura highlighted exporters converting Dollar revenues into Yuan as another source of support in July.
A large trade surplus creates the potential for those conversions, although the amount retained in Dollars still matters to the actual currency demand.
UBS’s calendar lists trade figures the same day, after August’s $119.09 billion surplus.
For the Australian Dollar, stronger Chinese imports would offer a more encouraging signal than a surplus inflated by weak domestic demand.
Halpenny adds: “The continued CNY strength is helping isolate Asian currencies from the broader dollar gain. While the DXY has advanced 3.3% from the September low, the dollar against a basket of Asia FX is just 0.7% higher.”
Trade pressure changes the Euro comparison
He describes the 8 October People’s Bank of China paper as a “PBOC document defending the FX policy of China and arguing against the level of CNY as being the cause of China’s large trade surplus. Competitive gains within China’s manufacturing sector is the main driver of increase exports from China.”
His valuation assessment differs: “The release of this document by the PBoC suggests China isn’t budging. Is the CNY undervalued? The answer seems certainly yes although the scale of undervaluation is debated and while this undervaluation helps boost exports the FX factor is only a partial explanation.”
Nominal gains have not erased earlier losses in the Yuan’s trade-weighted, inflation-adjusted value.
Halpenny writes: “However, from the 2022 high the index fell 20% to last year’s low before 6.5% to today’s level. The IMF estimates an undervaluation of between 12% to 20% which is around the consensus range.”
On 9 October, EU trade commissioner Maroš Šefčovič announced an understanding to moderate Chinese hybrid-vehicle exports and improve European access to China’s market, while leaving final endorsement to EU leaders.
Progress reduces the immediate danger of an escalating dispute, but does not remove the competitive pressure on European manufacturers that makes EUR/CNY politically sensitive.
Brief FAQ
When are China’s next inflation figures due?
September consumer and producer prices are scheduled for 14 October 2026, with trade figures also listed that day in bank calendars.
Why has the Yuan held up against a stronger Dollar?
MUFG sees the daily PBoC fixing as a sign of tolerance for further Yuan gains, while export earnings provide potential currency support.
How could China’s data affect AUD/USD?
Stronger Chinese imports would support Australia’s export outlook more clearly than a surplus driven by weak Chinese domestic demand.