

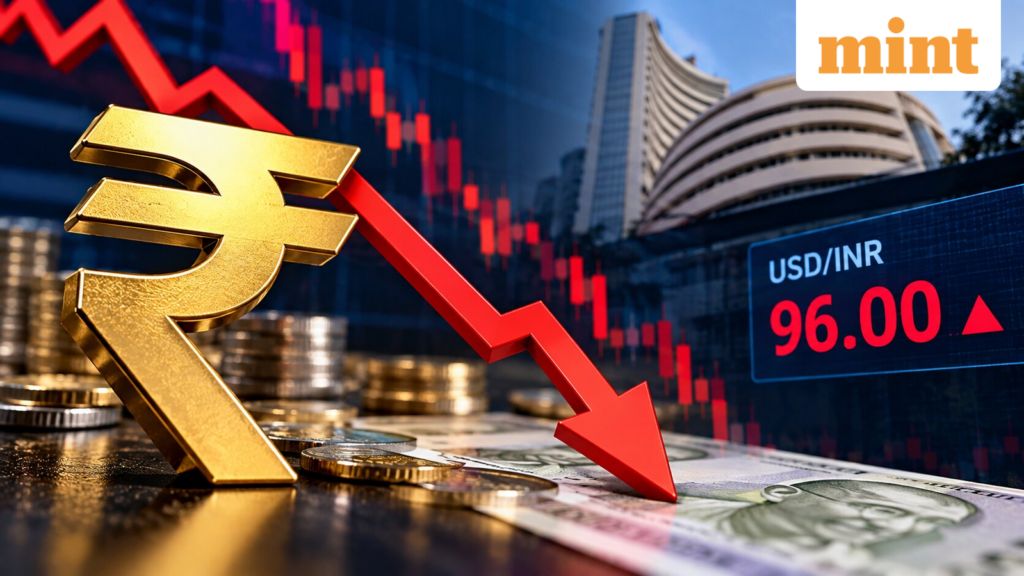
The Indian rupee weakened past the ₹96-per-dollar mark on Tuesday, 29 September, hitting a two-month low as rising crude oil prices intensified concerns over the impact on India’s import bill and triggered further worries over portfolio outflows.
The rupee fell to an intraday low of ₹96.1475 per dollar, down nearly 0.2%, before recovering some ground amid likely intervention by the Reserve Bank of India (RBI).
Meanwhile, Brent crude prices climbed 2% to $107.40 a barrel as concerns over supply disruptions in the Middle East following the US-Iran conflict outweighed signs of a recovery in crude exports from the region. Higher oil prices are a concern for India, which relies heavily on imports to meet its energy requirements.
The ongoing inflation, strong economic growth, and the anticipation of rising global interest rates are complicating the Reserve Bank of India’s policy outlook as it approaches its October monetary policy meeting. An increase in rates could bolster the rupee by raising the cost of betting against the currency and enhancing the appeal of Indian debt, especially at a time when equities have struggled to attract foreign investment.
Foreign investors have continued to be net sellers of Indian assets, with international investors offloading $3.7 billion in Indian stocks and bonds during September alone. This has brought their total outflows for the year to $19.6 billion, intensifying the pressure on the rupee.
Amit Pabari, MD, Research Team at CR Forex Advisors, said the RBI’s clear intent to defend the ₹96 level, coupled with continued swap inflows, is likely to keep the rupee’s upside limited. He identified ₹96.10– ₹96.20 as a key resistance zone, while a sustained break below ₹95.70 could pave the way for a move towards ₹95.20– ₹95.00.
Will it cross 97 in October?
Dr. V K Vijayakumar, Chief Investment Strategist at Geojit Investments, said two fundamental factors are driving the rupee’s weakness: rising crude oil prices and concerns that elevated prices could persist for an extended period, and renewed selling by foreign institutional investors (FIIs) in September after they turned buyers in July and August.
According to Vijayakumar, these factors are likely to widen India’s current account deficit, adding further pressure on the rupee. However, he expects the currency to remain below the 97-per-dollar mark in October, as the Reserve Bank of India (RBI) is likely to intervene at lower levels, he said.
Tushar Badjate, Director of Badjate Stock & Shares Pvt Ltd, said the rupee could breach the ₹97-per-dollar mark in October, although it is not a given. He attributed the pressure to three factors: crude oil prices near $106 per barrel amid the effective closure of the Strait of Hormuz; US 10-year Treasury yields above 5.2%, with markets pricing in more Fed rate hikes; and continued foreign outflows from Indian equities.
Badjate said the RBI is defending the currency, but a sharp fall in foreign exchange reserves in a recent week suggests that its interventions have so far only slowed the rupee’s decline. He identified two developments that could alter the currency’s direction: a credible roadmap for reopening the Strait of Hormuz, which could ease pressure on oil prices and bond yields, and the RBI’s policy decision on 7 October. In the absence of either development, the risk remains tilted towards further weakness, making a move through ₹97 possible, though he said he would not assign a precise level.
Prathamesh Kadival, Research Analyst at Bonanza, said whether the rupee crosses ₹97 in October will largely depend on crude oil prices, geopolitical developments, US interest rates and RBI intervention. He said the level is certainly possible if oil prices remain elevated and foreign outflows continue, although RBI intervention could help limit sharp currency movements.
Rupee depreciation – What does it mean for Indian stock market?
Dr. V K Vijayakumar, Chief Investment Strategist at Geojit Investments, said the rupee’s depreciation so far is not significant enough to have a major impact on investors.
However, Tushar Badjate, Director of Badjate Stock & Shares Pvt Ltd, said the impact varies across asset classes and sectors. In equities, he noted that a weaker rupee often coincides with foreign selling, which has been the case recently. IT and pharmaceutical exporters could remain relatively resilient as they earn a significant portion of their revenues in dollars. In contrast, oil marketing companies, airlines, paints, autos and companies with high dollar-denominated debt or imported inputs could face margin pressure due to higher costs. Badjate also pointed out that a weaker rupee reduces dollar-denominated returns for foreign investors, potentially extending selling pressure.
On fixed income, Badjate said rupee weakness, combined with elevated crude oil prices, could push up inflation expectations, creating a headwind for bonds and prompting the RBI to be more cautious about monetary easing. For personal finances, he said that imported goods, fuel-related expenses, overseas education, and foreign travel could become more expensive. Investors holding global funds or US stocks may see higher returns when converted into rupees, but he cautioned that currency depreciation should not be treated as investment return.
Prathamesh Kadival, Research Analyst at Bonanza, said the impact of a weaker rupee on investors is mixed. Export-oriented sectors such as IT and pharmaceuticals could benefit from stronger-dollar revenues, while oil & gas, aviation, chemicals, and other import-dependent businesses could face higher input costs and margin pressure.
Disclaimer: This story is for educational purposes only. The views and recommendations above are those of individual analysts or broking companies, not Mint. We advise investors to check with certified experts before making any investment decisions.