

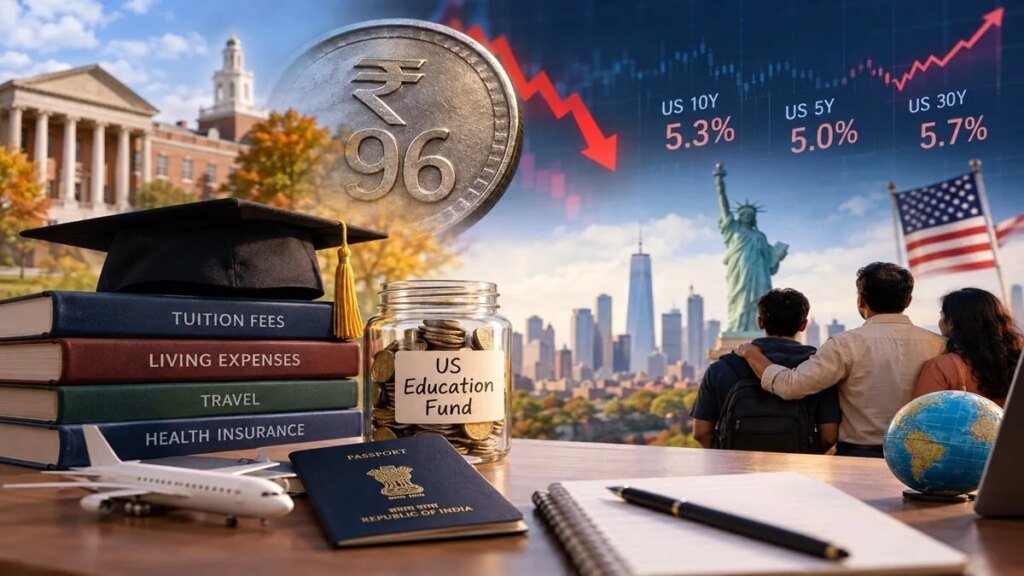
The dream of sending a child to a US university is getting more expensive for Indian families. The problem is not only rising tuition fees.
The reason is not just rising college fees. The Indian rupee has fallen sharply against the US dollar, while US bond yields have climbed to multi-decade highs. Together, the two developments have changed the mathematics of saving for a foreign education.
The rupee was trading around Rs 96.85 against the US dollar on October 7. It is close to its record low of Rs 96.96. The currency has lost around 7.5% against the dollar so far in 2026. The weakness has come despite the Reserve Bank of India raising the repo rate by 25 basis points to 5.50% on Wednesday, its first rate hike in nearly four years.
At the same time, US Treasury yields have moved sharply higher. The 10-year US Treasury yield touched about 5.35% on October 7, its highest level since 2002, while the 30-year yield rose above 5.7%. The 5-year Treasury yield was around 5.06% based on the latest available official data.
For Indian parents who have dreams to send their children to the US for higher education, the impact is easy to understand.
If a university charges $50,000, the fee remains $50,000. But the rupee amount required to pay that fee changes with the exchange rate. At Rs 85 to a dollar, $50,000 would cost Rs 42.5 lakh. At Rs 96.85, the same $50,000 costs about Rs 48.4 lakh. That is a difference of nearly Rs 6 lakh for just one year’s expense. The university has not increased its fee by even a dollar.
This is why parents planning for a US education need to look at the currency risk along with investment returns.
Your education target is actually a dollar target
A parent may think that the goal is to build a Rs 1 crore or Rs 2 crore corpus. But if the child is going to study in the US, the actual liability is in dollars.
That changes the way the goal should be planned. The total cost will depend on tuition fees, living expenses, healthcare, travel and other costs. It will also depend on the exchange rate when the money is actually needed.
The College Board’s latest data shows that the average published tuition and fees for out-of-state students at public four-year colleges in the US was $31,880 in 2025-26. For private non-profit four-year colleges, the average was $45,000. Once living expenses and other costs are included, the average annual student budget was around $50,920 for public colleges and $65,470 for private colleges.
This means a four-year education can easily run into several hundred thousand dollars.
For an Indian family, the rupee value of that amount can change significantly over four years.
Rajan Sarkar, Director and Unit Head at Anand Rathi Wealth, says parents need to consider several factors while planning.
“Investors should understand that US education cost is influenced by multiple factors such as forex rates, US education inflation and those borrowing to fund the education cost should also consider about bond yields as education loan for overseas studies, interest rates are generally linked to the lender’s benchmark, such as the MCLR While US bond yields do not directly determine Indian education loan rates, higher global yields can keep financial conditions tight and put upward pressure on domestic borrowing costs.”
This creates a double challenge. A weaker rupee increases the rupee cost of the education. Higher borrowing costs can increase the cost of an education loan if the family needs to borrow.
Why US bond yields matter
US bond yields may appear unrelated to a child’s education plan. But they matter indirectly. The US 10-year Treasury yield was around 5.3% on October 7. The 30-year Treasury yield was above 5.7%.
The 5-year US Treasury yield was also around 5%. These are high yields compared with the levels seen in recent years. Higher US yields can make dollar assets more attractive to global investors. This can support the dollar and put pressure on currencies such as the rupee.
India’s 10-year government bond yield was also around 7.2% on October 7. Bond yields have also risen in several other developed markets. UK 10-year gilt yields were above 5% on October 7. For parents, however, the important point is not where global bond yields go next. It is whether the portfolio can meet the future dollar requirement.
What should parents do if the child is 3-5 years away?
A three-to-five-year time frame is not very long for a large financial goal. Parents should not take too much risk just because they want to maximise returns.
At the same time, they cannot ignore inflation or currency depreciation. The approach should gradually change as the child’s admission date gets closer.
Sarkar says parents with a three-to-five-year time frame should consider having some exposure to stable dollar-denominated assets.
“3 to 5 year time-frame is generally very shorter time-line, ideal strategy should be for investors to park portion of allocation in dollar denominated stable assets which helps to maintain stability and currency hedging.”
The important point is that parents do not need to move the entire corpus into dollars immediately. They can gradually build the dollar allocation. They should also keep reviewing the target. A target fixed five years ago may no longer be enough today. The rupee may have weakened. Tuition fees may have increased. Living costs may also be higher.
Should parents start buying dollars?
Parents should not try to predict the exact rupee-dollar rate. Nobody knows whether the rupee will be at Rs 95, Rs 100 or Rs 90 when the child starts college.
Instead, the focus should be on reducing the risk of having to convert the entire corpus at one exchange rate.
Sarkar suggests gradually increasing the dollar allocation as the admission date approaches.
“Parents can consider to maintain some portion of allocation towards dollar based investments when nearing to child’s admission, particularly for expenses that will be incurred in the dollars. Since the future liability is dollar-denominated, holding a portion of the corpus in US-dollar assets can provide a natural hedge against rupee depreciation.”
He, however, does not suggest moving the entire portfolio into dollar assets.
“However, we suggest to avoid taking an aggressive shifting the entire education corpus into dollar assets. The allocation should increase progressively as the goal approaches and should be determined by the expected timing and size of the dollar liability. Parents can begin with a modest dollar allocation and gradually increase it during the final 1 to 2 years before the child starts college.”
This is essentially about matching the investment with the future expense. If the expense is going to be in dollars, having some dollar-linked assets can reduce the impact of a weaker rupee.
Are US bonds more attractive now?
US Treasury yields above 5% may look attractive to Indian parents saving for a US education. But parents should not look at the yield alone. The future expense is in dollars. So a dollar-denominated fixed-income investment can provide both a dollar asset and an income from that asset.
Sarkar says: “Elevated US bond yields do make US fixed-income instruments relatively more attractive from a yield perspective. However, for an Indian parent saving for a foreign education, the decision should not be soley based on the yield differential alone. If the future education expenses are in US dollars, holding a portion of the corpus in US-dollar fixed-income assets can provide a natural currency hedge, while also generating income on the dollar allocation.”
There is one important risk to remember. Bond prices can fall when yields rise. So parents should not simply chase the highest yield. The maturity of the investment should also match when the money is required.
If the money is needed in two years, taking a large exposure to a long-duration bond can create unnecessary volatility. The objective of an education corpus is different from that of a long-term wealth portfolio. The money has to be available on time.
What should parents do in the final 2-3 years?
This is perhaps the most important part of the planning. When the child is still seven or eight years away from college, parents can take more investment risk. But that changes when the child is just two years away.
A market crash at that point can seriously damage the education corpus. There may not be enough time for the portfolio to recover.
Sarkar suggests moving a large part of the amount required for the first one to two years of education into stable assets.
“For investors when they are nearing to the goals in next 1 or 2 years it is suggested to gradually reducing the portion of the education corpus from equity to other relatively stable assets like debt instruments and one can consider to shift 70–80% of required amount for the first 1–2 years of education expenses to relatively stable, high-quality fixed-income and other low-volatility assets.”
He says the focus should change as the goal gets closer. “The remaining portion can continue to have some growth-oriented exposure with 80:20 equity & debt. However, when nearing the goals priority should be to shift from return maximisation to capital preservation, liquidity and certainty of funding.”
The message is clear. Once the education goal is close, protecting the money becomes more important than chasing higher returns.
Stagger your dollar purchases
There is another way parents can reduce currency risk. They do not necessarily have to convert a large amount into dollars on a single day. Instead, they can stagger their remittances based on the payment schedule.
Adhil Shetty of BankBazaar says currency movements are difficult to predict.
“The most useful shift is in planning, not necessarily in which assets are held. Currency movement is hard to predict, so the corpus should be built with the payment date in mind. As that date nears, staggering remittances rather than converting a lump sum reduces the risk of converting at an unfavourable rate.”
This does not eliminate currency risk. But it reduces the risk of making the entire conversion at an unfavourable exchange rate. Parents should also keep revisiting the target corpus.
“Families should also revisit their target corpus periodically, since a weaker rupee can quietly widen the gap between what was saved and what is needed.”
That is an important point. The education target should not be a number that is decided once and forgotten. It should be reviewed regularly.
What happens if the rupee falls further?
Consider a parent who expects to need $200,000 for the first two years of education. At Rs 85 to a dollar, the requirement would be Rs 1.70 crore. At Rs 90, it becomes Rs 1.80 crore. At Rs 96.85, it is around Rs 1.94 crore. At Rs 100, it becomes Rs 2 crore.
| Dollar requirement | Rs 85/$ | Rs 90/$ | Rs 96.85/$ | Rs 100/$ |
|---|---|---|---|---|
| $50,000 | Rs 42.5 lakh | Rs 45 lakh | Rs 48.4 lakh | Rs 50 lakh |
| $100,000 | Rs 85 lakh | Rs 90 lakh | Rs 96.85 lakh | Rs 1 crore |
| $200,000 | Rs 1.70 crore | Rs 1.80 crore | Rs 1.94 crore | Rs 2 crore |
This is why a parent should build some cushion into the education corpus. If the rupee weakens further, the answer should not automatically be to take more equity risk.
The parent should first calculate the new shortfall. Then look at how much additional savings can be made. The family can also consider scholarships, financial aid or an education loan for part of the requirement.
The important thing is to identify the shortfall early. Waiting until the admission date is close can leave very few options.
Don’t let the rupee decide your child’s education plan
The current market is a reminder that foreign education is not just an investment goal. It is a foreign-currency liability. A parent may build a large rupee corpus and still fall short if the rupee weakens sharply. This is why the strategy should change as the goal approaches. With five years or more to go, parents can focus more on growth.
With three to five years left, they should start giving more importance to currency risk and stable assets. With one to two years left, the focus should increasingly be on capital protection and liquidity. A gradual dollar allocation can also help.
US bond yields above 5% make dollar fixed-income assets worth considering for parents with a genuine dollar liability. But the decision should not be based on yield alone.
The maturity, liquidity, currency exposure, taxation and the timing of the education expense all matter. The biggest mistake would be to wait for the perfect exchange rate. Parents cannot control where the rupee will trade when the tuition bill arrives. They can, however, control how much of the future dollar requirement has already been protected. For a US education goal, that may be more important than chasing the highest possible return.
Disclaimer: This story is for informational purposes only and should not be considered investment or financial advice. The investment approach and asset-allocation views mentioned are based on expert opinions and may not be suitable for every investor. Parents should assess their financial goals, risk appetite, investment horizon, tax implications and the timing of education expenses before making investment decisions. Currency rates and bond yields can change, and dollar-denominated investments carry currency, market and other risks.
Every financial journey has a turning point. What’s yours?
Financial Express is launching a new series highlighting real experiences with money, investments, and the taxman. Did a sudden tax rule catch you off guard? Did a piece of financial advice change your life? Your story could provide invaluable, practical lessons for thousands of fellow taxpayers. Share your experience with us. We respect your privacy: no stories will be featured without a direct conversation and your full consent. Thank you.